
Most homeowners know the big-picture reason they have homeowners insurance. If something serious happens to the house, insurance is there to help protect them financially. But the details can get a little fuzzy.
What happens if your neighbor’s tree falls on your roof? What if your laptop is stolen while you’re on vacation? Does homeowners insurance cover a busted water pipe? What about the expensive jewelry tucked away in your bedroom?
The answer to almost every insurance question starts in the same place: it depends on your policy and what caused the loss.
Still, there are some situations where homeowners are often surprised by what their policy may—or may not—cover.
Here are seven worth knowing.
1. A Tree Falls on Your House
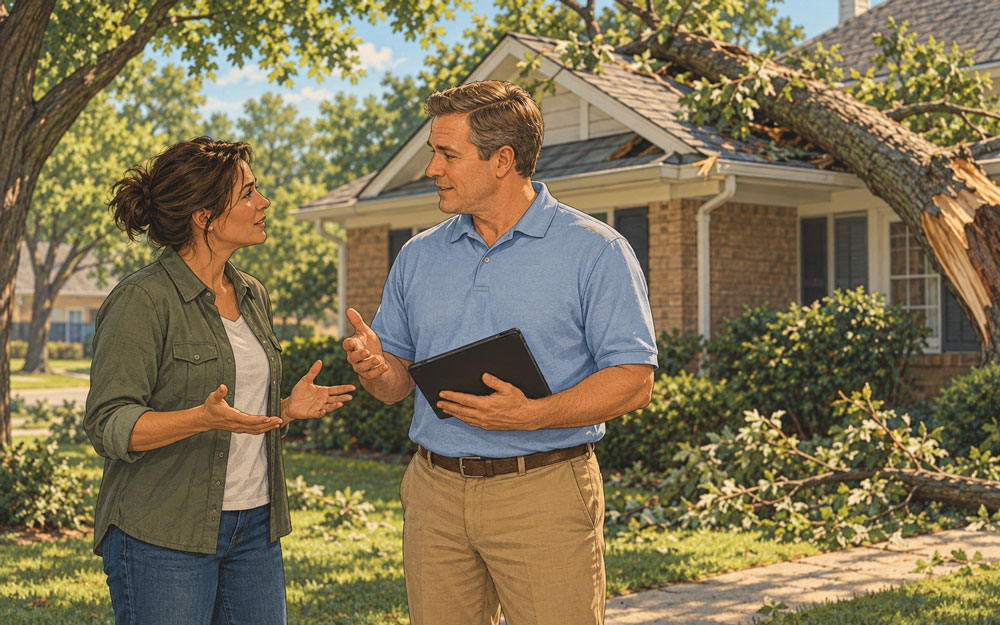
If a tree falls on your home because of a covered event such as wind or a storm, your homeowners policy may help pay for damage to the house and, in some cases, removal of the tree. But here’s where it gets interesting: whose tree it was may not be the most important question.
If your neighbor’s otherwise healthy tree comes down during a storm and damages your home, your own homeowners insurance may be the policy that responds. If the tree was obviously dead or neglected and the neighbor knew about it, the situation could be different. The cause and circumstances matter.
2. Water Damage Isn’t All the Same
This is one of the biggest sources of confusion for homeowners. If a pipe suddenly bursts inside your house and damages the flooring, walls or furniture, your homeowners policy may provide coverage for that damage.
If water rises from outside your home during heavy rain or flooding, that’s generally a different story. Standard homeowners policies typically don’t cover flood damage, which is why separate flood insurance may be important for Mississippi homeowners. Same water. Very different insurance situation.
3. Your Belongings May Be Covered Outside Your House
Your homeowners insurance doesn’t necessarily stop protecting your belongings when they leave your driveway.
If your laptop, luggage or other personal property is stolen while you’re traveling, your policy may provide some coverage—even though the loss happened hundreds of miles from home. There may be limits, deductibles and exclusions involved, so it’s worth knowing how your particular policy handles personal property away from your residence.
4. Someone Gets Hurt at Your House
Homeowners insurance isn’t only about repairing the house. Most homeowners policies include some form of personal liability coverage. If a guest slips on your steps, gets injured around your pool or is hurt in another incident for which you’re legally responsible, your policy may help with certain medical expenses, legal costs or damages. The amount of liability protection you have matters, particularly if you have a pool, trampoline, pets or other circumstances that could increase your exposure.
5. Expensive Stuff May Have Limits
You might look around your house and assume all of your belongings are simply covered under the personal property portion of your policy. But, certain categories of property—such as jewelry, firearms, collectibles, artwork or other high-value items—may have specific coverage limits, particularly for certain types of loss.
For example, having $100,000 of personal property coverage doesn’t automatically mean every individual item you own is protected up to its full value.
Depending on what you own, additional coverage or specifically listing certain items on the policy may make sense.
6. What You Paid for Your House Isn’t Necessarily What It Costs to Rebuild It
Your home’s market value and its reconstruction cost are two different numbers. You may have purchased your house for $300,000, but that doesn’t necessarily mean $300,000 would rebuild it after a major loss. Construction materials, labor costs, demolition, debris removal and changes in building costs can all affect the amount needed to rebuild.
That’s one reason reviewing your dwelling coverage periodically can be important, especially after renovations or significant changes in construction costs.
7. Some of the Biggest Gaps Aren’t Obvious Until Something Happens
Homeowners insurance can cover a lot, but no policy covers everything.
Flooding, certain types of water damage, maintenance issues, normal wear and tear and other circumstances may be excluded or require separate coverage. Even when something is covered, deductibles and coverage limits can affect how much the policy pays. Unfortunately, the worst time to discover one of those details is after you’ve already had a loss.
Know What You Have Before You Need It
You don’t need to memorize your insurance policy. That’s what we’re here for. But it is worth occasionally asking a few questions:
What does my policy actually cover?
What are my limits?
What isn’t covered?
And has anything changed since we last reviewed it?
At Runnels Insurance, we believe insurance should make sense before you need to use it. As an independent insurance agency serving Mississippi, we can help you review your current coverage, identify potential gaps and understand the options available to you.
Because when something unexpected happens, understanding your coverage shouldn’t be another surprise.